
Serving Lucas, Ottawa, Sandusky and Wood Counties
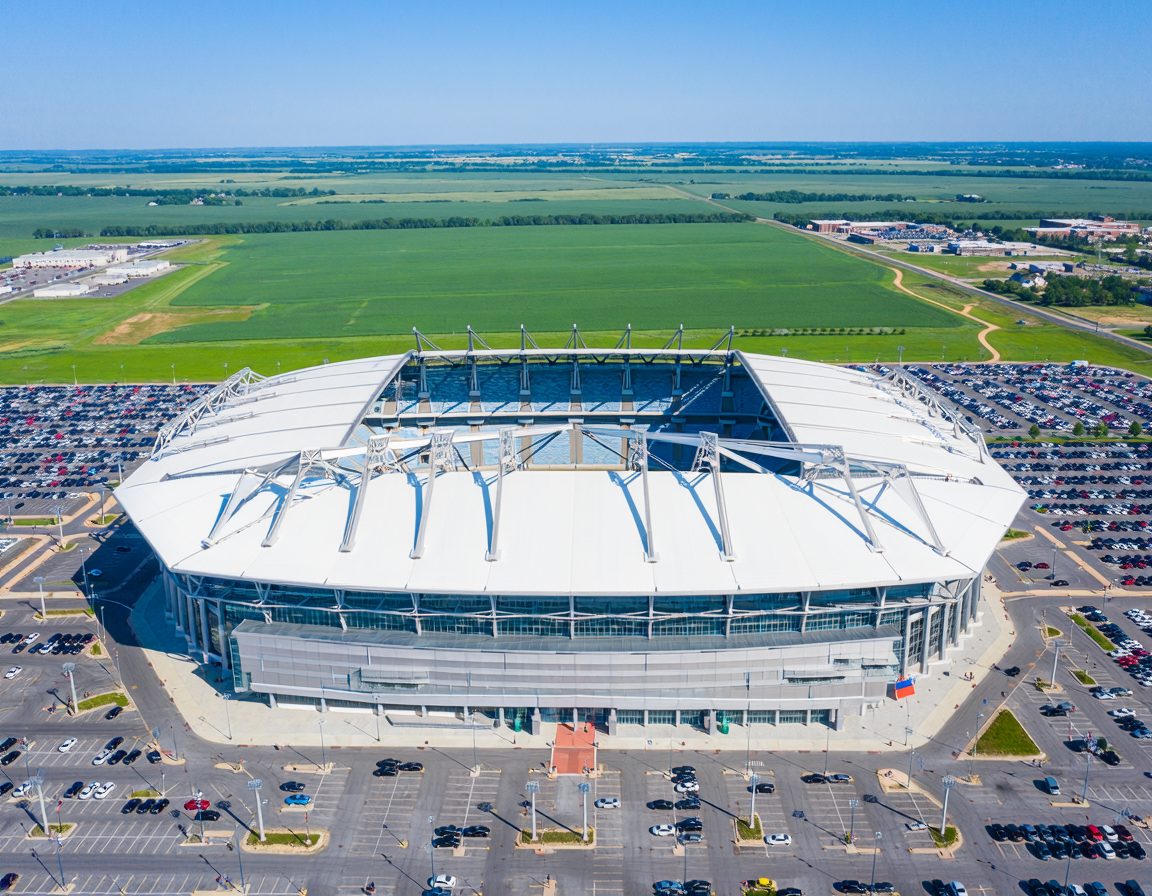
When a team makes a pitch for a new stadium, the first thing most community members want to know is how much it will cost them. The answer depends on how the deal is structured. Most modern venue deals follow a similar pattern, and teams typically bear a significantly greater share of the cost than they did 20 or 30 years ago..
Andrea Austin, a shareholder at Greenberg Traurig who negotiates sports venue deals for public owners and professional teams, says understanding that structure, often referred to as the capital stack, helps cities, teams, and taxpayers see where the money comes from and what each side is responsible for.
In a typical deal today, team ownership puts in significant private equity and arranges private financing for the building itself. Austin says that commitment is the foundation of everything else.
Public partners and lenders expect owners to put their own money at risk. They also expect a long-term commitment to the community, not a short stay until a better offer comes along.
Public funding is usually limited to infrastructure, such as roads and transit improvements that serve the venue and the area around it. Austin says the reason is straightforward. Elected officials want to avoid asking residents to directly subsidize a venue that mainly benefits a privately owned team – “handouts to billionaires” is a headline no public official wants to campaign on..
Keeping public money focused on infrastructure also means the investment serves the community on the days when there is no game, particularly with respect to mixed-use neighborhoods that are increasingly prevalent components of sports venue developments.
Austin points to three common types of funding sources for the public portion of a deal:
Many deals combine more than one of these sources.
Before committing, public partners and lenders vet the team closely. Austin says that starts with a team covenant not to relocate, often backed by a penalty clause that requires the team to repay the public debt and additional damages if it leaves before the debt is paid off.
They also look hard at the ownership group’s finances to confirm it can meet its commitments. And they assess the owners’ ties to the community, since a deal works best when ownership is invested in the city for the long haul.
Host cities should also step back and look at the bigger picture. Austin, whose work includes negotiating non-relocation and community benefit agreements, recommends asking four questions:
Austin says the goal is a long-term partnership that is a net positive for the community. A deal built on real private investment, focused public spending, and clear protections for taxpayers has the best chance of getting across the goal line.
About Andrea Austin
Andrea Austin is a shareholder in Greenberg Traurig’s Denver office. She focuses her practice on the development, operation, and renovation of professional sports facilities, representing public owners and professional teams in new venue projects, renovations, and public-private partnerships.
Disclaimer: This article is intended for informational purposes only and does not constitute legal, financial, or investment advice. The views and opinions expressed herein reflect those of the individuals quoted and do not represent an endorsement of any company, product, or service mentioned. Readers should conduct their own due diligence and consult qualified professionals before making any investment decisions.
Disclosure: Individuals or companies mentioned may have a commercial relationship with KeyCrew.


